

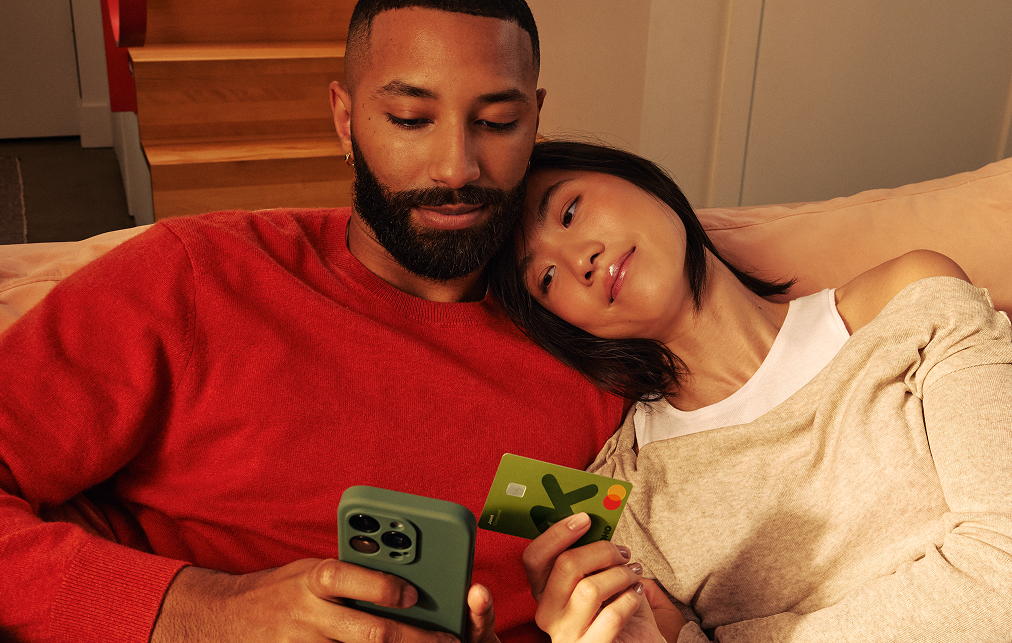
Earn up to 3.5% interest on every dollar of your savings with KOHO
Personal finance automation is the process of setting up your income, savings and bill payments to run automatically.
In Canada, you can use direct deposit, scheduled transfers and pre-authorized payments to manage your money with less manual effort.
The smartest approach is to automate predictable expenses while keeping enough flexibility to handle unexpected costs.
KOHO High Interest Savings
It is a prepaid Mastercard, so you spend your own money while still earning high interest.
With KOHO High Interest Savings, you can:
Grow your savings up to 3.5% interest
Earn a 2% cash back rate on groceries, eating, drinking, and transportation and 0.5% cash back on everything else
Unlimited transactions and free e-transfers
No minimum balance required, ever
1. Set Up Direct Deposit
Start by having your employer deposit your paycheque directly into your primary spending account.
This provides a predictable starting point for your financial automations.
If you're paid biweekly, you can schedule savings transfers and bill payments around those dates rather than relying on the calendar month.
2. Automate Your Savings
Set up an automatic transfer each payday to move a portion of your income into savings.
For example, you could automatically transfer:
$100 toward an emergency fund
$50 toward a vacation
$150 toward a future home purchase
Start with amounts that fit comfortably within your budget.
You can increase your contributions as your income grows or expenses decrease.
3. Schedule Your Bill Payments
Many Canadian service providers support pre-authorized debits for recurring expenses such as:
Utilities
Insurance
Internet
Phone bills
Mortgage payments
A pre-authorized debit allows an organization to withdraw an agreed amount from your account according to your authorization.
You can also arrange recurring bill payments through your financial institution when supported.
Review your bills regularly to make sure the amounts are correct.
4. Automate Your Credit Card Payments
Automatic credit card payments can help you avoid missed due dates.
If you can afford it, consider setting up automatic payment of your full statement balance.
This can help you avoid purchase interest when your card provides an interest-free grace period.
Keep enough money in your account to cover the payment, particularly if your balance changes significantly from month to month.
5. Set Up Recurring TFSA or RRSP Contributions
If you're saving for longer-term goals, you can arrange regular contributions to a TFSA or RRSP.
For example, you might contribute a fixed amount every payday rather than making one large contribution at the end of the year.
However, automation does not remove contribution limits.
Track your available contribution room across all your accounts before setting up transfers.
6. Keep a Buffer for Automatic Payments
One of the biggest risks of automating your finances is scheduling more withdrawals than your account can cover.
For example, if rent, insurance and several subscriptions are withdrawn on the same day, your balance could become too low.
Keep a small buffer in your spending account and space out transfers when possible.
This can help you avoid declined payments, NSF fees and overdraft charges.
How Often Should You Review Your Finances?
Automation should reduce repetitive work, not eliminate financial oversight.
Review your accounts at least once a month to check:
Upcoming payments
Unnecessary subscriptions
Savings progress
Account balances
Changes in income or expenses
Adjust your automatic transfers whenever your financial situation changes.
What's the Smartest Way to Automate Your Money?
Build your system around payday.
Have your income deposited automatically, move an affordable amount into savings and schedule essential payments around your cash flow.
Keep enough money available for everyday expenses and review your accounts regularly.
The goal is to make saving and paying bills consistent without creating a system so rigid that an unexpected expense throws everything off track.
About the author
Quan works as a Junior SEO Specialist, helping websites grow through organic search. He loves the world of finance and investing. When he’s not working, he stays active at the gym, trains Muay Thai, plays soccer, and goes swimming.
Read more about this author