

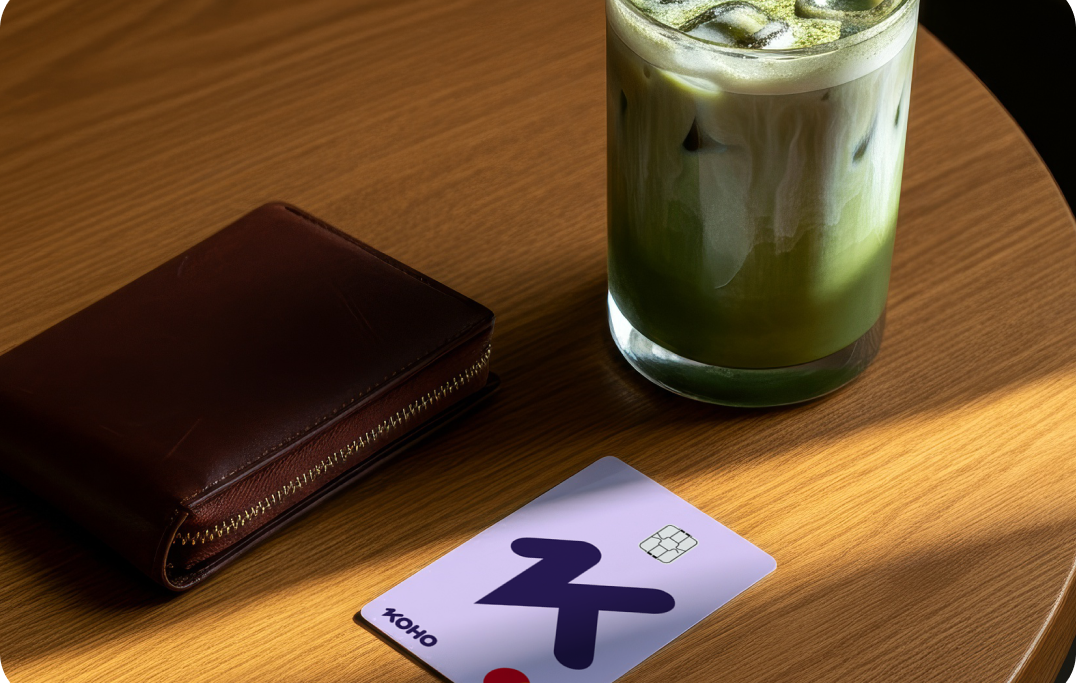
Earn up to 3.5% interest on every dollar of your savings with KOHO
A high-interest savings account can be a good place to keep money you want to grow without taking on investment risk.
The main advantages are easy access and higher interest than many standard savings accounts.
The main drawbacks are variable rates, possible fees and taxes on interest earned outside a registered account.
KOHO High Interest Savings
It is a prepaid Mastercard, so you spend your own money while still earning high interest.
With KOHO High Interest Savings, you can:
- Grow your savings up to 3.5% interest
- Earn a 2% cash back rate on groceries, eating, drinking, and transportation and 0.5% cash back on everything else
- Unlimited transactions and free e-transfers
- No minimum balance required, ever
Pros of a High-Interest Savings Account
Your money earns interest
The biggest advantage is that your savings can grow instead of sitting in an account that pays little or no interest.
The higher the rate, the faster your balance can grow.
Your money stays accessible
Unlike many GICs, a high-interest savings account generally allows you to withdraw your money when you need it.
That makes it useful for:
- Emergency funds
- Vacation savings
- Home down payments
- Large upcoming purchases
- Short-term financial goals
Lower risk than investing
Savings accounts do not fluctuate in value like stocks or ETFs.
If your deposit is eligible for deposit insurance, your money may also be protected up to applicable coverage limits.
Interest can compound
Some accounts calculate interest daily and pay it monthly.
Once interest is added to your balance, future interest can also be earned on that amount.
Cons of a High-Interest Savings Account
Interest rates can change
Most high-interest savings account rates are variable.
A financial institution can raise or lower the rate, so the return you earn today may not continue indefinitely.
Promotional rates can also expire.
Inflation can reduce your real return
Even if your account balance is growing, your purchasing power can fall if inflation is higher than your savings rate.
For example, earning 2% while prices rise 3% means your money is growing more slowly than the cost of living.
Interest may be taxable
Interest earned in a regular non-registered savings account is generally taxable income in Canada.
If you hold eligible savings inside a TFSA, the interest can generally grow tax free.
Some accounts have restrictions or fees
Depending on the provider, you may encounter:
- Monthly fees
- Minimum balance requirements
- Withdrawal limits
- Transaction fees
- Transfer restrictions
Always check the account terms rather than comparing only the advertised interest rate.
Is a High-Interest Savings Account Good for an Emergency Fund?
Yes.
A high-interest savings account can work well for an emergency fund because the money remains accessible while still earning interest.
That is usually more practical than locking emergency savings into a long-term investment or non-redeemable GIC.
Is a High-Interest Savings Account Good for Long-Term Investing?
Usually not as your only strategy.
A savings account is useful for preserving cash and short-term goals, but long-term investments such as diversified stocks or ETFs may offer greater growth potential.
The trade-off is that investments can lose value.
A high-interest savings account is therefore better suited to money you may need soon or cannot afford to put at risk.
Is a High-Interest Savings Account Worth It?
It can be.
A high-interest savings account is most useful when you want:
- Easy access to your money
- Low risk
- A better return than a standard savings account
- A place for short-term savings
It is less suitable when your main goal is maximizing long term growth.
The best approach is to match the account to the purpose of the money rather than choosing solely based on the highest advertised interest rate.
About the author
Quan works as a Junior SEO Specialist, helping websites grow through organic search. He loves the world of finance and investing. When he’s not working, he stays active at the gym, trains Muay Thai, plays soccer, and goes swimming.
Read more about this author